I recently had the opportunity to share ADI’s latest research on the U.S. midstream oil and gas industry at the 10th Annual OCTG & Line Pipe Forecast Summit. My presentation explored how oil and gas production growth, LNG export expansion, and increasing power demand are driving a new wave of midstream investment. As illustrated in Exhibit 1, North American crude oil production is expected to grow by 0.4% to 3.3% annually through 2030, while natural gas production is projected to rise by 1.4% to 2.7% annually, supporting continued demand for midstream infrastructure.
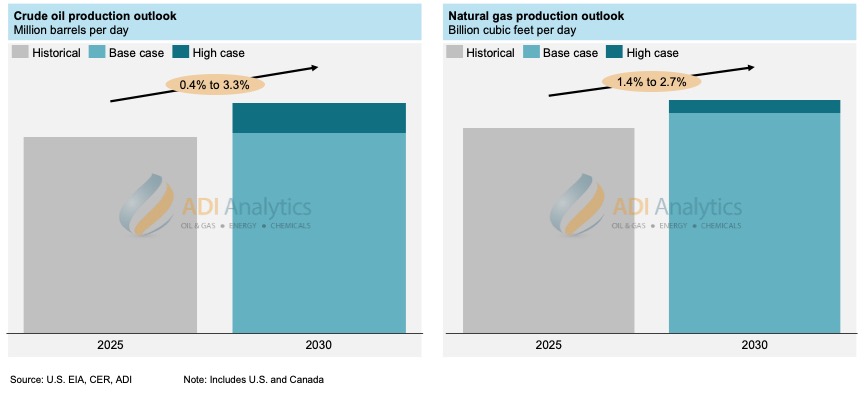
Exhibit 1. North American crude oil and gas production outlook.
While the industry spent much of the last decade focused on crude oil takeaway capacity from major shale basins, future growth opportunities are increasingly concentrated in natural gas transportation, processing, storage, and NGL infrastructure. This shift reflects changing demand patterns and evolving infrastructure constraints across key producing regions. Exhibit 2 highlights some of the most attractive growth opportunities across the U.S. midstream value chain.
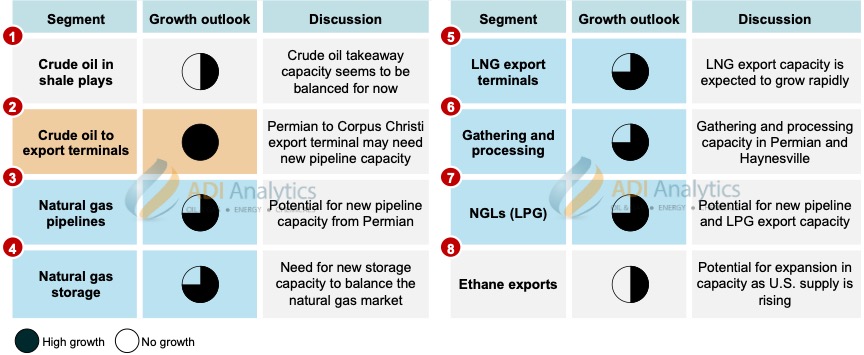
Exhibit 2. Growth opportunities in U.S. midstream.
Infrastructure needs are becoming increasingly regional. While some basins are approaching capacity limits, others retain sufficient infrastructure to accommodate future production growth. At the same time, expanding LNG exports and rapidly growing power demand from data centers are creating new sources of demand that may prove just as important as traditional industrial and residential consumption. As a result, investment decisions are increasingly influenced by infrastructure utilization, proximity to demand centers, access to export markets, and regulatory considerations, in addition to production growth.
ADI Analytics recently evaluated production outlooks alongside existing and announced pipelines, processing, fractionation, and storage infrastructure across key U.S. producing regions to assess how midstream investment opportunities are evolving through the end of the decade. The report includes a detailed, play-by-play assessment of oil, natural gas, and NGL production growth, existing capacity, utilization trends, and announced midstream projects to identify where infrastructure additions may be required and where existing networks can accommodate future growth.
The rest of this article is available to ADI Plus Essential subscribers. Enhanced subscribers also get a downloadable PDF including basin-level production and infrastructure outlooks, inventories of existing and announced pipelines, capacity forecasts, and detailed analysis of announced midstream projects across major U.S. producing regions. For Enterprise subscribers, an additional data file is also available.
Log in or subscribe to unlock ADI Plus content >>
Have questions? We're happy to help.
About ADI Analytics
ADI is a prestigious, boutique consulting firm specializing in oil and gas, energy, and chemicals since 2009. We bring deep expertise in a broad range of markets where we support Fortune 500, mid-sized and early-stage companies, and investors with consulting services, research reports, and data and analytics, with the goal of delivering actionable outcomes to help our clients achieve tangible results.
We also host the ADI Forum that brings c-suite executives together for meaningful dialogue and strategic insights across the oil & gas, energy transition, and chemicals value chains. Learn more about the ADI Forum.
Subscribe to our newsletter or contact us to learn more.